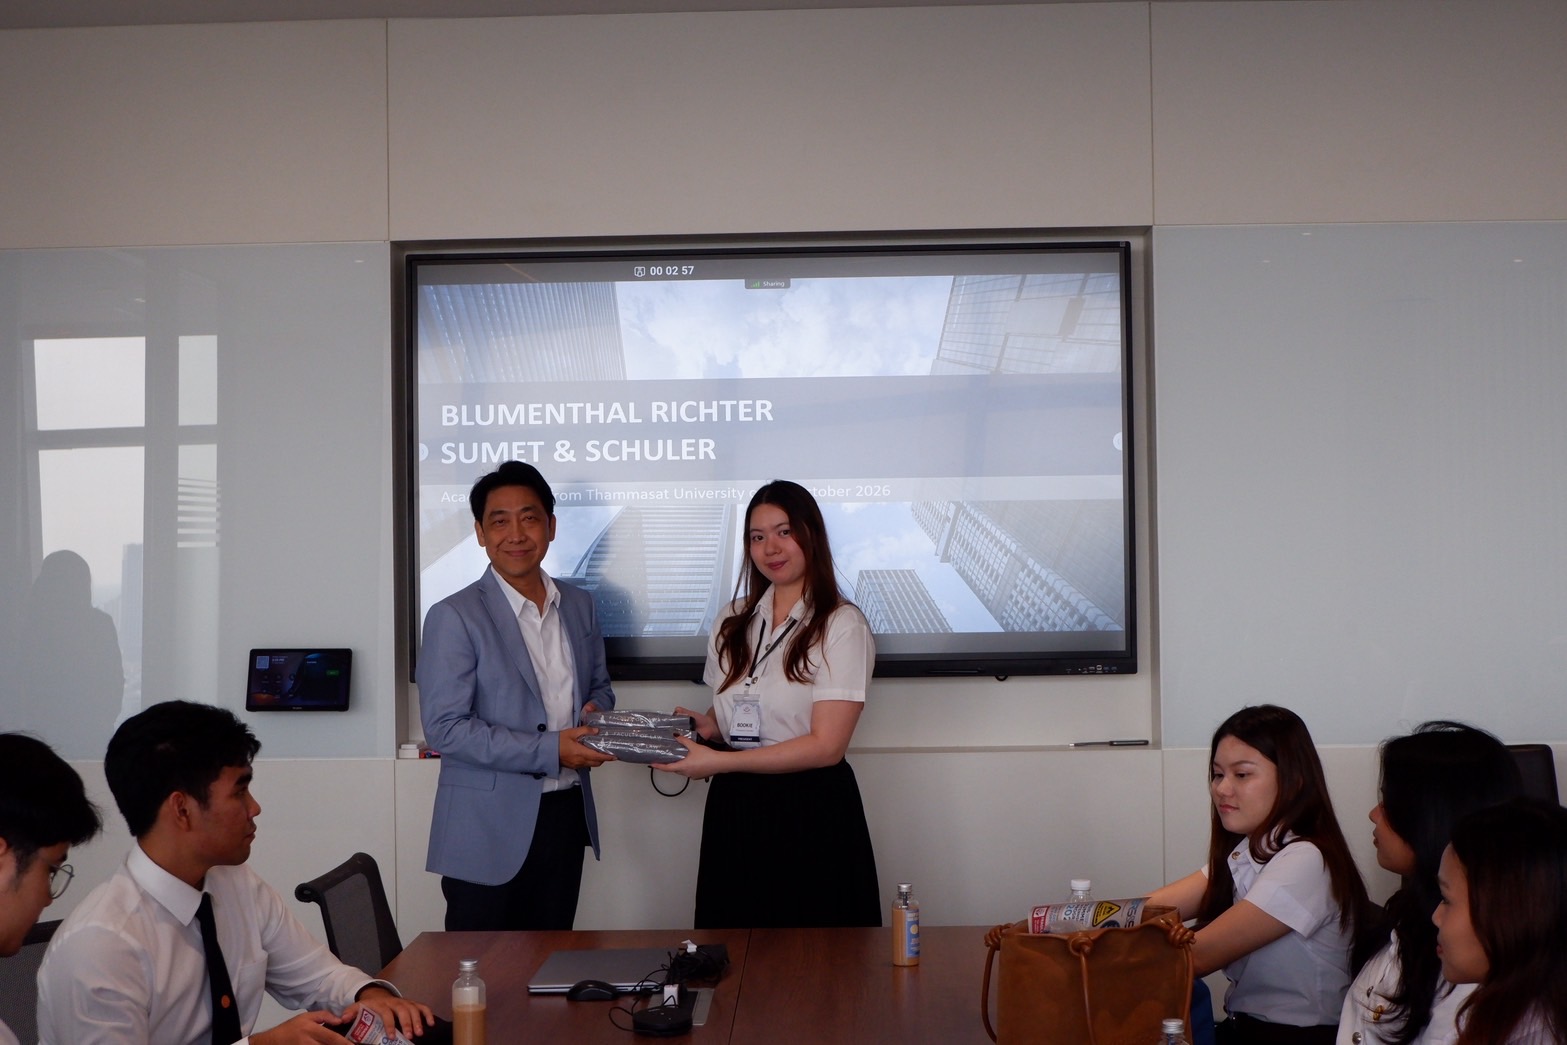
On 5 November 2026, Blumenthal Richter Sumet & Schuler (BRS&S) hosted “Tax Issues on Deductible Expenses for CIT”, a discussion session at our office. The session offered practical insights into expense deductibility for corporate income tax in Thailand.
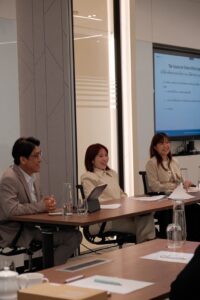
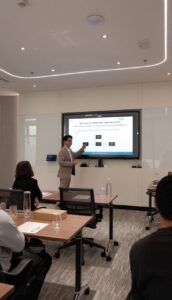
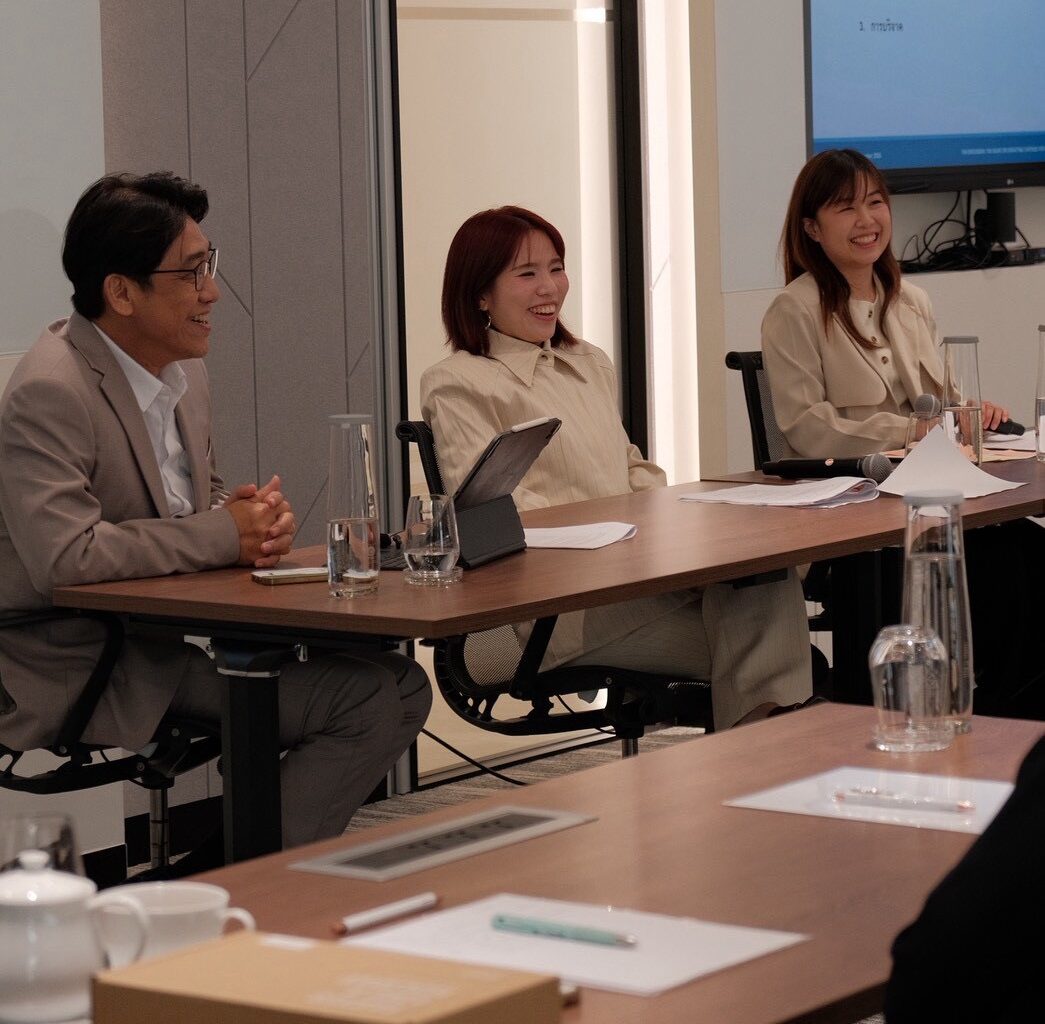
The session was led by our Tax and Customs team: Senior Partner Sumet Mingmongkolmitr, Senior Associate Sudarat Jirakietwattana and Associate Warumporn Chaosanguan. The speakers guided participants through the legal principles, applicable tax regulations and relevant rulings from the Thai Revenue Department regarding the deductibility of expenses for corporate income tax purposes.
The session provided a platform for speakers and participants to exchange knowledge and practical experiences. The speakers shared real-world scenarios and discussed challenges with the Thai Revenue Department regarding the deductibility of expenses. Through practical case studies, the speakers analyzed the tax implications and offered insights into how the applicable tax principles are identified in practice.
The participants were also encouraged to raise questions from their own business operations and share their perspectives. This interactive exchange enabled participants to gain a deeper understanding of the relevant tax treatment and practical approaches to managing tax risks in their business activities.
We thank all participants for joining and for contributing to such an engaging discussion.